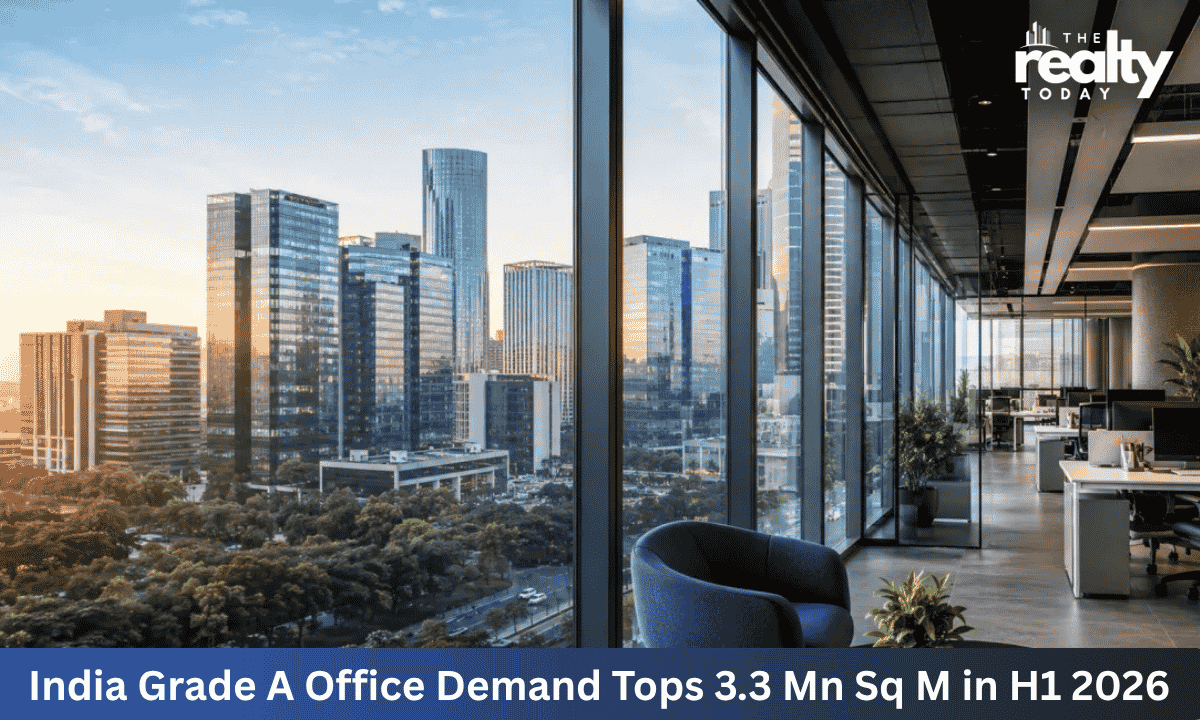
India’s Grade A office market remained strong in the first half of 2026. Demand continued to stay ahead of new supply across the country’s leading office markets. Grade A office net absorption reached 3.32 million sq m in H1 2026 across India’s top seven cities, according to Colliers. New Grade A office completions stood at 2.09 million sq m during the same period. This was 9% lower than a year earlier.
With demand growing faster than supply, the vacancy rate fell to 15.2%, down 101 basis points year on year. Average office rents also increased by around 7.5% during the period.
The numbers point to continued demand for high-quality office space even as businesses remain cautious because of global trade and economic uncertainty.

Demand is running ahead of supply

India leads office demand in Asia Pacific
India's office market is also becoming an important driver of the wider Asia Pacific market. Across 11 major Asia Pacific office markets, leasing activity reached 4.6 million sq m in H1 2026, up 3% from a year earlier. India, Mainland China and Japan together accounted for more than 95% of regional office leasing. India alone contributed more than 70% of leasing activity across these key markets.
New office supply across the 11 markets fell 37% year on year to around 3 million sq m. India and Mainland China accounted for more than 80% of this new supply.

Global Capability Centres remain a key driver
Global Capability Centres, or GCCs, continue to support office demand in India. GCCs are offices set up by global companies to handle functions such as technology, research, finance, analytics and other business services. Their expansion has become an important source of demand in India's major office markets.
According to CBRE, GCCs absorbed around 19.6 million sq ft of office space in H1 2026. This accounted for 43% of India's total office leasing during the period. GCC leasing also increased 17% year on year. In Q2 alone, GCC leasing reached an all-time high of around 10.3 million sq ft.

Bengaluru remains a major office market
India's leading technology and business hubs continued to account for a large part of office demand. CBRE data shows that Bengaluru, Delhi-NCR and Mumbai accounted for about 61% of total office absorption in H1 2026.
Bengaluru remained the largest leasing market. In Q2 2026 alone, Bengaluru accounted for 27% of India's office leasing activity. Bengaluru, Pune and Delhi-NCR together accounted for around 58% of Q2 leasing.
The strong performance of these cities reflects their large technology, financial services and corporate sectors. It also highlights the continued concentration of high-value office demand in established business locations.
Flexible offices are gaining ground
The office market is also changing in terms of the type of space companies want. Flexible office operators were the largest occupier segment in Q2 2026, accounting for 27% of leasing activity.
Technology companies accounted for 21%, while banking, financial services and insurance companies accounted for 13%. Together, flexible workspace operators, technology companies and BFSI firms drove nearly 62% of Q2 leasing.
The demand shows that companies are looking for offices that can provide flexibility while still offering good quality and location.
Green buildings are becoming more important
Sustainability is another major trend in India's office market. About 76% of new office completions in Q2 2026 were green-certified. Around 73% of leasing activity during the quarter was concentrated in green-certified buildings. This indicates that environmental standards are becoming a more important part of office decisions for both developers and occupiers.
Green buildings can also support companies as they work towards their environmental targets and improve workplace quality.

What does this mean for the office market?
The H1 2026 numbers show that India's office market continues to have strong underlying demand. The most important trend is the gap between demand and new supply.
Occupiers are taking more space while developers are adding supply at a slower pace. This has helped reduce vacancy and support rental growth. The preference is also shifting towards better-quality buildings. Grade A offices, green-certified assets, flexible spaces and well-connected business locations are attracting strong interest.
GCC expansion is adding another layer of demand. Global companies continue to use India for technology, research, analytics and other business functions. CBRE expects GCCs to account for more than 40% of total office absorption in 2026. The outlook, however, is not without risks.
Global trade conditions, geopolitical tensions and changes in technology hiring could affect corporate expansion plans. For now, India's office market appears well placed to maintain its momentum.
The first half of 2026 has already delivered record office absorption, strong Grade A demand and rising rents. If demand continues to stay ahead of supply, the pressure on rents and vacancy could remain visible in India's major office markets through the second half of the year. India is not simply adding more office space. The market is seeing stronger demand for quality, flexibility, sustainability and global-standard workplaces.