
Residential sales across India's eight largest cities held at 258,238 units in the first nine months of 2026, in line with the same period last year. Developers launched 279,899 units, up 4%. Knight Frank describes a market that is plateauing after several years of strong growth.
Launches keep outpacing sales
In July–September, sales slipped 1% year on year to 86,767 units, while launches rose 4% to 92,549. Launches have now exceeded sales for 16 consecutive quarters. Over the nine months, the gap stands at about 21,700 units. Launches are units offered for sale for the first time.

NCR is the only major market to decline
NCR sales fell 11% to 35,574 units. The other seven markets together rose 2%. Mumbai remained the largest market at 72,804 units (+1%), its highest nine-month volume since 2018. The city accounted for 28% of sales and 26% of launches, with 72,673 units launched, up 13%. Bengaluru recorded 43,140 units (+5%) and Pune 36,402, broadly unchanged. Hyderabad, Ahmedabad, Chennai and Kolkata grew 2–4%.
Demand shifts to higher price bands
Homes priced above ₹1 crore accounted for 55% of sales, up from 50% a year earlier. The share of homes below ₹50 lakh fell to 18% from 22%. The ₹2–5 crore segment grew fastest, rising 19.4% to 51,501 units. The ₹1–2 crore band remained the largest at 77,087 units, or 30% of sales. Sales below ₹50 lakh declined 14% to 47,660 units.

NCR's ₹5–10 crore segment is the weak spot
Sales in this band fell 39% to 4,033 units, against 5,002 launched. Gurugram accounts for 57% of NCR's unsold inventory. The ₹2–5 crore segment, by contrast, continued to grow across most major markets, including NCR.
Absorption is slowing
Quarters to sell, the time needed to clear existing inventory at the current sales pace, rose to 6.1 in July–September from 5.8 a year earlier. This is the fourth consecutive increase and the highest since April–June 2023. It remains below the 7–11 quarters recorded between 2018 and 2021. Prices rose in every tracked market. Bengaluru recorded 11% annual growth, which Knight Frank says may partly reflect higher-priced stock entering its inventory-weighted average. Elsewhere outside NCR, growth ranged from 3% to 6%.
Reading the plateau
Shishir Baijal, chairman and managing director of Knight Frank India, says the market is entering a more selective phase, where “quality and relevance of supply will matter as much as the strength of demand.” He reads the shift to higher ticket sizes and the gradual rise in quarters to sell as normalisation rather than a broad slowdown. The macro backdrop remains supportive. GDP grew 7.8% in April–June, above the RBI's 7% projection, and the repo rate was held at 5.25%. Knight Frank notes that monetary policy is no longer adding momentum. In sum, sales are steady, supply is rising and prices are firm.
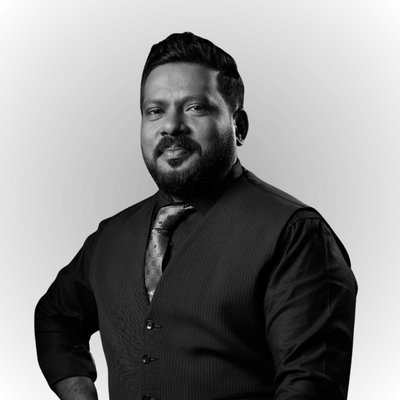
Mr. Suresh H. A., Managing Director, Sanjeevini Group,
"Bengaluru continues to stand out in the national residential market, with moderate growth in homes sold and launches. More importantly, the city’s performance comes against an all-India market where sales remained flat, indicating the strength of Bengaluru’s employment, infrastructure and end-user demand. The sustained appetite for ₹1–5 crore homes, with significant absorption in the ₹2–5 crore segment shows growing premiumisation. While rising prices are making buyers more discerning, the underlying demand remains healthy, particularly for well-located, quality housing. This gives us confidence in Bengaluru’s medium-to-long-term residential outlook."
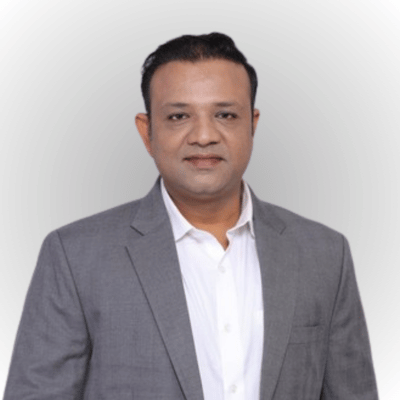
Mr. Lalit Parihar, Managing Director, Aaiji Group, a real estate firm,
"The 9M CY2026 numbers indicate that the residential market is moving through a phase of consolidation rather than losing its underlying momentum. Nationally, sales remained broadly stable, even as launches grew 4%, reflecting continued developer confidence and healthy end-user demand. Ahmedabad’s moderate growth in both sales and launches is encouraging in this context. Demand is increasingly moving towards higher-value housing, while the mid-to-premium segments remain important growth drivers. This combination of stable volumes, competitive prices, measured supply and gradual premiumisation provides a constructive outlook for the market."