
Four years ago, 85 out of every 100 new homes launched in India's top cities cost less than ₹1.5 crore. Today, that number has fallen to 47, while homes priced above ₹4 crore have grown nine-fold. This is not a short-term dip. It's a four-year structural shift, backed by fresh data from CareEdge Ratings and reported by Business Standard and it's reshaping who builders are building for across India's top seven cities.
The Headline Number: Affordable Housing's Share Has Crashed
In Q1 2022, homes priced below ₹1.5 crore made up 85% of all new launches across India's top seven cities. By Q1 2025, that share had fallen to 57%. By Q1 2026, it dropped further to just 47%.
Meanwhile, the segments above it have grown sharply:
₹1.5–4 crore homes: up from 14% of launches in Q1 2022 to 44% in Q1 2026
Homes above ₹4 crore: up from just 1% to 9%, a nine-fold increase in share
Here's how that shift looks across the three years:
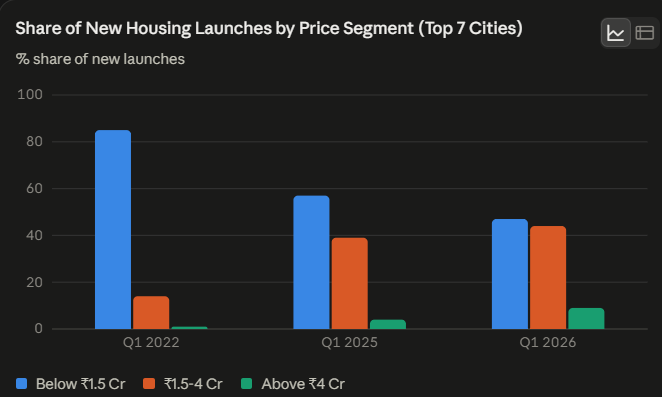
Put simply: for every two homes launched today, roughly one now costs over ₹1.5 crore. Four years ago, that was true for just one in seven.
Why Developers Are Moving Upmarket
CareEdge points to a mix of cost pressure and demand pull. Land acquisition, construction, and compliance costs have climbed enough to squeeze the economics of affordable housing projects. At the same time, demand from affluent domestic buyers and NRIs — who want larger homes with premium amenities — has stayed strong and is far less sensitive to inflation than the affordable and mid-income segments.
Rajashree Murkute, Senior Director at CareEdge Ratings, frames it as developers responding to where the viable margins and steady demand now sit: mid-premium and luxury housing.
The result is a widening divide. Affordable and middle-income demand has softened under inflation, elevated prices, and affordability constraints — even as premium and luxury segments stay resilient.
Developers Are Also in Much Healthier Financial Shape
This shift is happening alongside a sharp improvement in developer balance sheets. The debt-to-collections ratio for the top 13 residential developers has fallen from 1.80 times in FY20 to a record low of 0.68 times in FY26.
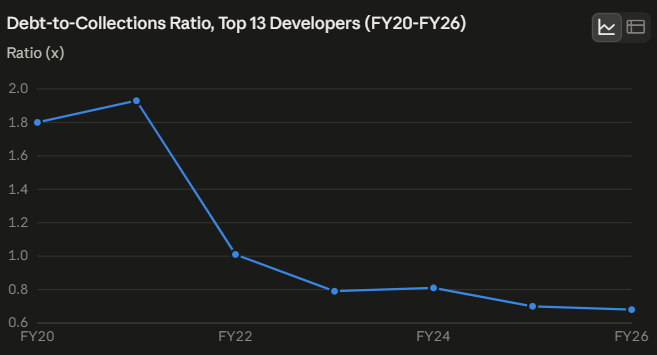
Source: CareEdge Ratings data
Chart for reference to make info
Debt-to-Collections Ratio — Top 13 Residential Developers (FY20–FY26)
The ratio actually rose slightly to 1.93x in FY21 before beginning a steady decline which is 1.01x in FY22, 0.79x in FY23, 0.81x in FY24, 0.70x in FY25, and 0.68x in FY26.
CareEdge attributes this deleveraging to three things:
Healthy collections — which crossed ₹90,000 crore in FY26 from sizeable launches
Fundraising-led debt reduction
Greater financial discipline across leading players
Bookings, meanwhile, exceeded ₹1.5 lakh crore. With debt staying broadly flat, that collections growth has built a real financial cushion for large developers, one that should help them absorb higher construction and energy costs, interest-rate swings, and near-term demand uncertainty.
The catch: this cushion isn't evenly distributed. Smaller and mid-sized developers, with thinner balance sheets and narrower portfolios, remain more exposed.
A North-West vs South Divide in Housing Demand
Overall housing sales across the top seven cities dipped by a low single-digit percentage in Q1 2026 versus Q1 2025 but that headline number hides a sharp city-by-city split.
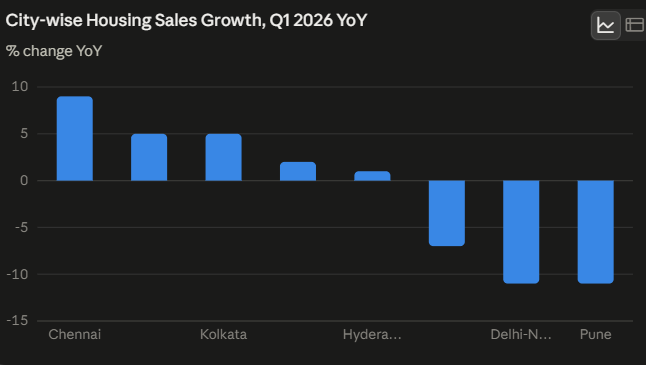
Cities where sales grew:
Chennai: +9% — the strongest growth among all top cities
Bengaluru: +5%
Kolkata: +5%
Ahmedabad: +2%
Hyderabad: +1%
Cities where sales fell:
MMR (Mumbai): -7%
Delhi-NCR: -11%
Pune: -11%
The pattern is fairly clear. Pune, Delhi-NCR, and MMR — markets that saw the steepest price appreciation over the past few years — are now seeing the sharpest pullback. CareEdge links this to affordability pressure, a natural cooling after a strong multi-year upcycle, and cautious buyer sentiment amid geopolitical and financial-market uncertainty.
Southern and eastern markets tell a different story. Chennai, Bengaluru, Kolkata, and Ahmedabad have held up better, helped by steady end-user demand, employment-linked housing needs, comparatively affordable pricing, and continued new project activity.
What This Means Going Forward
Three threads are worth watching:
Affordability is becoming a structural issue, not a cyclical one. With sub-₹1.5 crore launches nearly halved as a share of supply in four years, first-time and budget buyers have fewer new options to choose from — regardless of where rates or sentiment move next.
Developer resilience is now a story about balance sheets, not just sales volume. A sub-1x debt-to-collections ratio gives large players room to ride out a soft patch. Smaller developers without that cushion may be the ones to watch if demand stays soft.
The city-level divergence looks durable, not seasonal. Southern and eastern markets are working from a lower price base and steadier end-user demand — both of which tend to be stickier than sentiment-driven demand in high-priced western and northern markets.